


Payment infrastructure key to financial inclusion
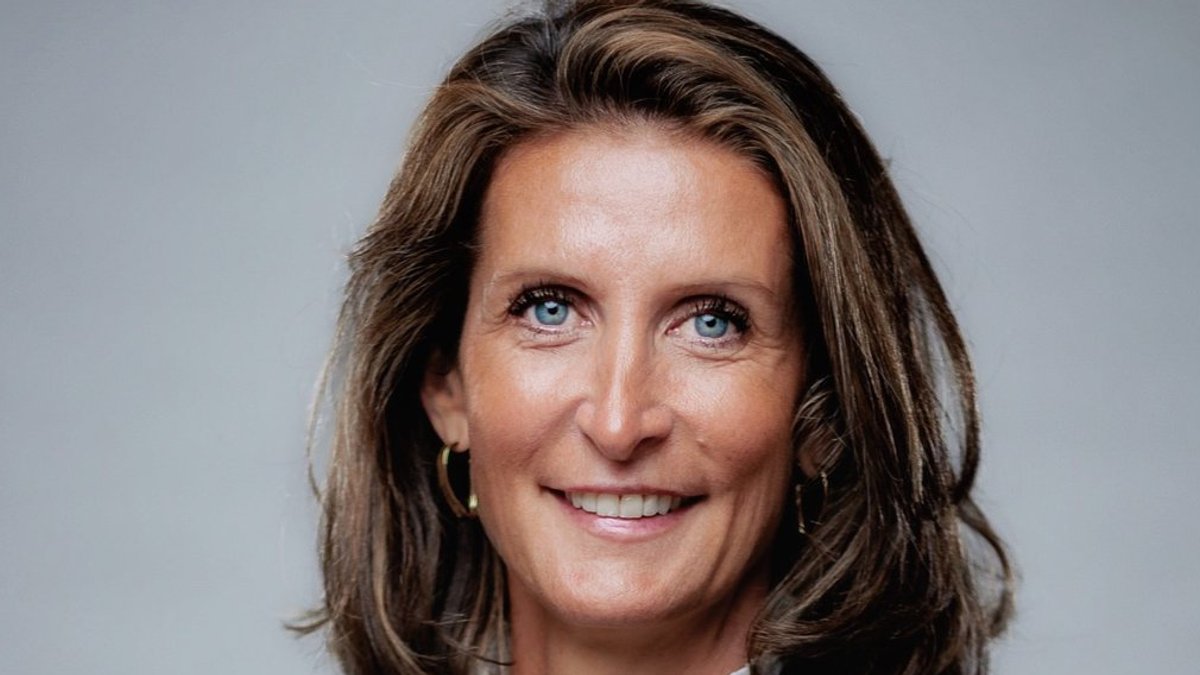
For millions of people, cross-border payments are a financial lifeline that underpins everyday survival, but the infrastructure powering global payments remains fragmented, opaque, and frequently overlooked in conversations around financial inclusion. According to Chloé Mayenobe, Deputy CEO of Thunes, the challenge today is that payments are still “highly fragmented”.
Thunes provides the infrastructure that helps money move more efficiently across borders, and Chloé says the company is solving the gap between domestic and cross-border payment experiences. “Sending money domestically can often feel instant and seamless, but once that payment moves internationally, the experience can change completely,” she says.
Payment Infrastructure and Financial Inclusion
Chloé argues that payment infrastructure should be treated as a central pillar of financial inclusion rather than a background concern. Payment infrastructure tends to be overlooked because it operates in the background, but it is fundamental to financial inclusion. Without interoperability, systems remain fragmented, which creates barriers to moving money across borders, making transfers more expensive and less accessible overall.
The global average cost of remittances remains at 6.36%, more than double the UN’s 3% target. Financial inclusion is not just about access to accounts – it’s also about usability. If systems don’t connect, people and businesses cannot fully participate in the economy.
One of the biggest barriers to seamless cross-border payments is a lack of interoperability across systems, between banks, mobile wallets, real-time payment networks, and emerging digital assets. Legacy infrastructure, which wasn’t designed to connect with modern technologies, leads to inefficiencies and delays. The last-mile delivery also remains a challenge, ensuring funds reach the end user quickly and reliably across local payment methods.
Research carried out with Juniper Research shows that 61% of people receiving international payments have experienced issues such as missed bills, financial strain, or the need to borrow money over the past few years due to delays in receiving funds. For the most vulnerable, remittance-dependent users, this rises to 83%. The consequences go beyond short-term disruption, directly affecting financial stability and wellbeing.
Related Post: Banks adapt custody for digital and traditional assets
Changing Expectations and the Role of Fintechs
Expectations are shifting quickly toward real-time, fully transparent payments. Speed has become the primary driver, with 56% of users ranking instant transfers as the most important feature, surpassing cost or security. Transparency also remains a challenge, with 41% of users not always shown the final amount upfront, creating uncertainty and undermining trust.
Fintechs play a critical role in expanding access to financial systems. By simplifying cross-border payments and enabling real-time transactions, they can smoothen financial processes for people or businesses who would traditionally be left behind. For underserved groups like gig-workers, this is especially pertinent, as they are more than twice as likely to rely on cross-border payments and often face higher fees.
The most impactful policy changes would focus on increasing interoperability across jurisdictions. Better alignment across frameworks, alongside more consistent technical standards, would make it much easier for systems to connect across borders. Initiatives such as SEPA have been very impactful in improving cross-border money movement across Europe, with faster, more cost-effective access.
New innovations in interoperability will have the biggest impact across the payments space over the next few years. As the connection between banks, mobile wallets, and the digital asset ecosystem continues to improve, consistency across markets will increase. However, interoperability is not only a fiat problem, as fragmentation risks expanding faster than anything seen in traditional payments.
As Chloé notes, it’s about removing friction at scale and making it easier for businesses to operate seamlessly while delivering a more consistent and inclusive experience for consumers. The connection between Thunes and its partners, such as banks and mobile wallets, is critical in achieving this goal, and the company is working to improve this connection across 140 countries.
Advancing Financial Inclusion through Collaboration
Collaboration between fintechs, banks, and regulators is essential in advancing financial inclusion. By working together, these stakeholders can build more connected global payment systems, reducing fragmentation and increasing access to financial services. Initiatives such as SEPA, which has improved cross-border money movement across Europe, demonstrate the potential for collaborative efforts to drive positive change. Similarly, the adoption of standard data formats like ISO 20022 has provided a shared language for banks and fintechs, facilitating greater connectivity and efficiency.


